FRS 102 Changes for 2026: What Accounting Teams Need to Know
FRS 102, the Financial Reporting Standard for the UK and Ireland, has been amended by the FRC in March 2024 with key changes to lease accounting (Section 20) and revenue recognition (Section 23) effective from accounting periods starting on or after January 1, 2026, requiring firms to recognize lease obligations on the balance sheet and update their accounting processes accordingly.
Lease Accounting
What is FRS 102? The Standard and Its 2026 Changes Explained
By: Jess Vento
Request a Demo
First Name*
Last Name*
Email*
Direct Phone Number*
What best describes your organization?*
Please SelectCPA FirmCompany - Non-ProfitCompany - PrivateCompany - PublicConsulting FirmChartered Accountancy FirmFractional CFOGovernmentPrivate Equity FirmOther
Which product(s) are you interested in?*
- Lease Accounting
- Data Extraction
- FRS 102
- BUCS
Lead Source Detail
UTM Source
UTM Medium
UTM Campaign
We'll only use your personal information to provide the products and services you've requested. From time to time, we'd like to contact you about other products and services that may be of interest to you. If you consent, please tick above to say how you'd like us to contact you.
- I agree to receive other communications from Crunchafi.
In order to provide you the content requested, we need to store and process your personal data. If you consent to us storing your personal data for this purpose, please tick the checkbox below.
- I agree to allow Crunchafi to store and process my personal data.*
You can unsubscribe at any time. See our Privacy Policy for details.
FRS 102 is The Financial Reporting Standard applicable in the UK and Republic of Ireland. In March 2024, the FRC published amendments to FRS 102 arising from its second periodic review, and most of these amendments are effective for accounting periods beginning on or after 1 January 2026. The main changes cover leases (Section 20) and revenue (Section 23).
If your firm or your clients hold leases, those obligations now appear on the balance sheet. Spreadsheets that worked before will not scale to what's required. Firms that start preparing now will close faster, carry lower audit risk, and avoid a last-minute scramble as the first year-ends under Section 20 close and accounts come due for filing in 2027.
Key Takeaways
- Most FRS 102 amendments are effective for accounting periods beginning on or after 1 January 2026. For most firms the biggest change is lease accounting.
- All sizes of UK/IE entities are affected, including large entities (£/€15m+), small entities (£/€1m–15m), and entities that are eligible to apply FRS 105 but instead choose to report under FRS 102.
- Short-term and low-value exemptions exist but must be documented. Applying them without a clear audit trail creates audit exposure.
- First-year adoption carries the highest risk. Transition calculations, opening balances, and disclosure completeness will receive heightened scrutiny.
What Is FRS 102 and Who Does It Apply To?
FRS 102 is the Financial Reporting Standard applicable in the UK and Ireland, issued by the Financial Reporting Council (FRC). It applies to most entities that are not using full IFRS, FRS 101, or FRS 105. This means the overwhelming majority of UK/IE companies. Publicly traded companies do not apply in most cases because they are required to adhere to the IFRS standards.
With the types of changes and the types of businesses that typically follow FRS 102, most entities are affected in practice because even a single office lease is typically material enough to require application of the standard and associated disclosures in the financial statements.
The 2026 update brings lease accounting and revenue recognition meaningfully closer to international standards without requiring full IFRS adoption.
One critical distinction for UK/IE accounting teams: because statutory accounts are filed publicly, every entity subject to FRS 102 is on record. Regulators, auditors, and lenders can access those filings. Errors or non-compliance carry real reputational and regulatory consequences.
What Is Changing in FRS 102 for 2026?
The March 2024 amendments to FRS 102 introduces two material changes for most accounting teams: a new lease accounting model under Section 20, and a revised five-step revenue recognition model under Section 23.
- Lease Accounting (Section 20): Operating leases, which were previously kept off the lessee’s balance sheet, must now be recognised as right-of-use assets and lease liabilities. This is a structural change to how lease obligations are presented, calculated, and disclosed in statutory accounts.
- Revenue Recognition (Section 23): FRS 102 now adopts a five-step model for revenue recognition, consistent with IFRS 15. Entities with complex contracts, variable consideration, or performance obligations spread over time will need to review how revenue is recognised.
Both changes take effect for periods beginning on or after 1 January 2026. For entities with a 31 December year-end, that means full compliance is required now. For entities with a 31 March year-end, the effective date is 1 April 2026.
The alignment with IFRS 16 is deliberate but not complete. Section 20 differs from IFRS 16 in five practical areas:
- Low-value assets: no monetary threshold, plus a list of nine asset categories that don't qualify as low value.
- Discount rates: when the rate implicit in the lease can't be readily determined, lessees can choose either their incremental borrowing rate or their obtainable borrowing rate, lease by lease.
- Modifications: three situations where lessees can keep the original discount rate instead of revising it.
- Disclosures: a full reconciliation of right-of-use assets and a maturity analysis for short-term and low-value lease commitments, with reduced requirements for small entities under Section 1A.
- Transition: modified retrospective approach only, with no restatement of comparatives, and a practical expedient for entities already applying IFRS 16.
For the full breakdown, read FRS 102 vs. IFRS 16: Key Differences Chartered Accountancy Firms Need to Know or download the side-by-side comparison guide (PDF).
FRS 102 March 2025 Amendment
In March 2025, the FRC issued amendments to FRS 102 and FRS 105 ( UK company size thresholds and IE company size thresholds) to reflect changes in UK/IE company law introduced by The Companies (Accounts and Reports) (Amendment and Transitional Provision) Regulations 2024.
The amendments update the monetary thresholds used to determine whether a company qualifies as a small entity or a micro-entity. Under the revised thresholds, a small company must not exceed two of the following: turnover of £/€15 million (previously £10.2 million or €12 million), a balance sheet total of £/€7.5 million (previously £5.1 million or €6 million), and 50 employees. For micro-entities, the updated thresholds are turnover of £1 million (previously £632,000) or €900,000 (previously €700,000) and a balance sheet total of £500,000 (previously £316,000) or €450,000 (previously €350,000), with the employee limit remaining at 10.
These changes are purely a consequence of the legislative update and do not alter the underlying financial reporting requirements within FRS 102 or FRS 105. The practical effect is that some entities which previously fell outside the small or micro-entity regimes may now qualify, potentially reducing their reporting obligations. The amendments apply for financial years beginning on or after 1 January 2026.
What Are the Biggest Lease Accounting Risk Areas for FRS 102?
Lease accounting under the updated Section 20 is the most operationally complex change for the majority of firms and their clients. It is also where the risk of error is highest.
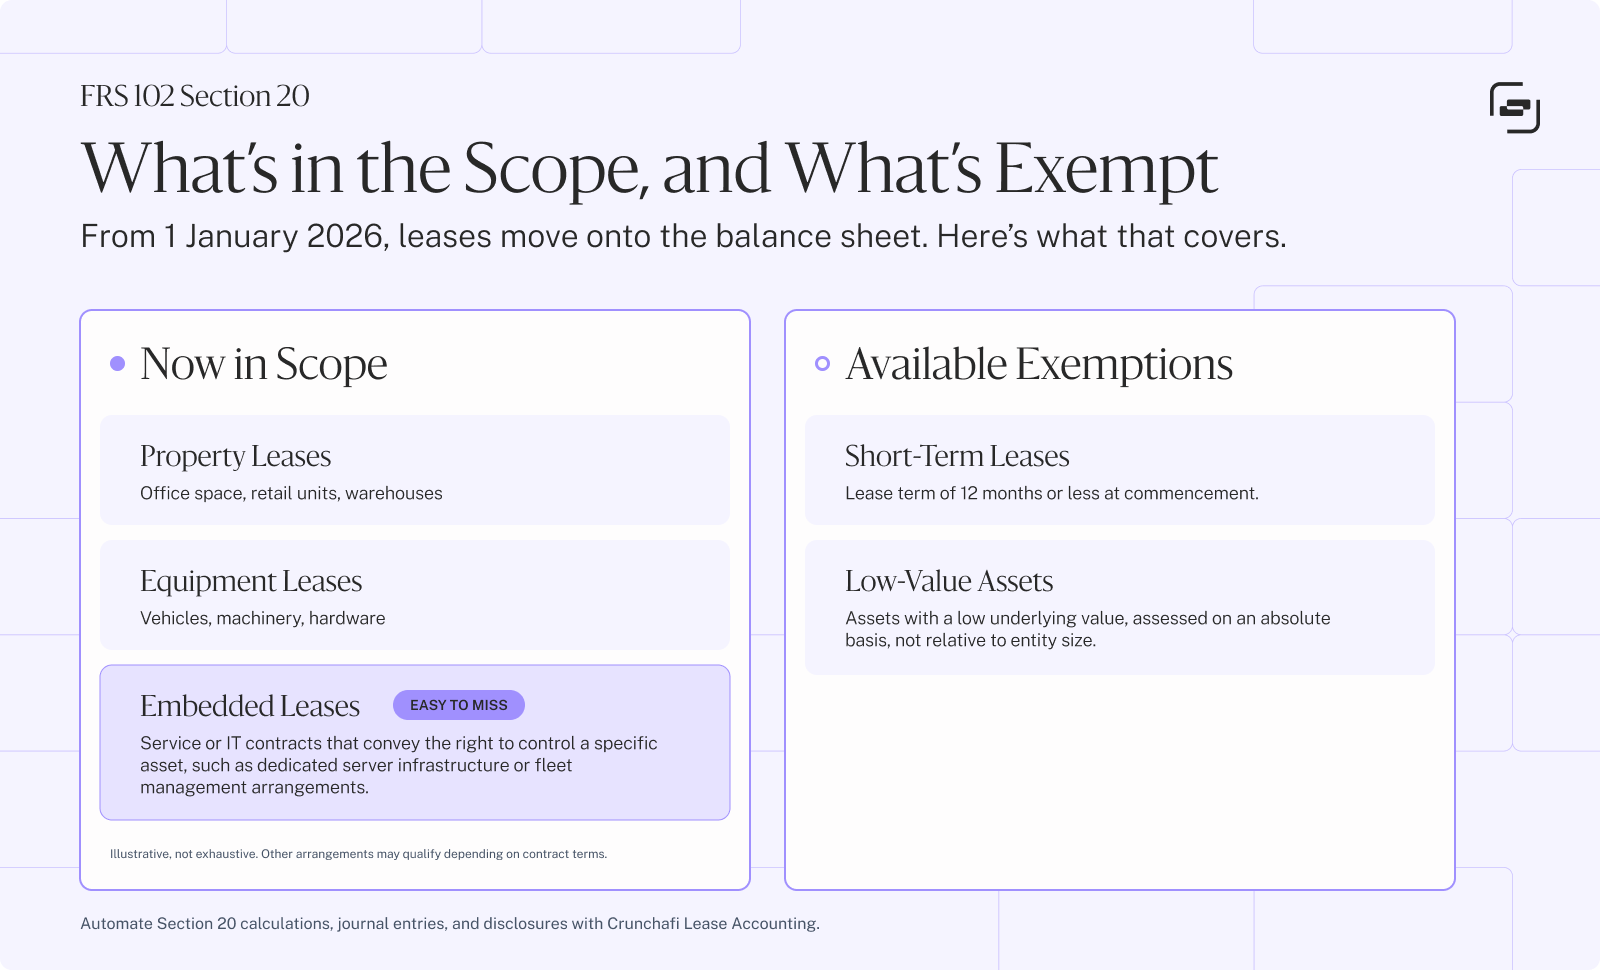
What's now in scope:
- Property leases (office space, retail units, warehouses)
- Equipment leases (vehicles, machinery, hardware)
- Embedded leases within service or IT contracts where the contract conveys the right to control a specific asset
This list is illustrative rather than exhaustive, and other arrangements may also fall within the updated lease definition depending on contractual terms.
That last category, embedded leases, is of great importance. A contract for dedicated server infrastructure or a fleet management arrangement may contain a lease under the updated definition, even if it was never treated as one before.
Available exemptions:
- Short-term leases: Leases with a term of 12 months or less at commencement may be excluded from on-balance-sheet treatment
- Low-value assets: Leases of assets with a low underlying value (assessed on an absolute basis, not relative to the entity's size) may also be excluded
Both exemptions must be assessed, documented, and disclosed where applicable, even when applied correctly under the standard. Applying them without a clear audit trail creates exactly the kind of exposure that auditors will scrutinise during the first post-transition cycle.
Why spreadsheets break here
The core calculations of discount rate application, right-of-use asset amortisation, and lease liability unwinding are manageable in isolation, but running them across a portfolio of leases in a spreadsheet and producing the more detailed Section 20 disclosures is where errors creep in. For the entries, worked examples and balance sheet impact, see our guide to FRS 102 Section 20 journal entries.
How Will FRS 102 Stress Busy Season Workflows?
The 2026 changes arrive at a crucial time. Here's what accounting for FRS 102 looks like in practice:
- More Data to Extract: Lease schedules, contract reviews, and embedded lease assessments require pulling data that wasn't previously tracked in structured form.
- More Judgements to Document: Short-term and low-value exemptions, discount rate selection, and performance obligation identification all require documented rationale, not just outputs.
- More Audit Scrutiny: First-year adoption is always the highest-risk period. Auditors will probe transition calculations, opening balances, and disclosure completeness.
- Less Time: With 31 December year ends predominating in the UK and Ireland, the post-transition busy season begins immediately.
Chartered accounting firms bear this implementation burden directly. The tool decisions made now will determine how efficiently they can serve clients through the first full compliance cycle and beyond.
Audit readiness requires more than accurate calculations. It requires journal entries that tie directly to balance sheet movements, disclosure outputs that meet the letter of Section 20, and a clear record of the judgments applied at each stage. Manual processes cannot reliably produce that at scale.
How Should Accounting Teams Prepare for FRS 102 Changes?
Preparation should be underway now. For entities with 31 December year ends, the first reporting period under the updated standard has already begun.
Practical steps:
- Identify All Contracts: Identify every arrangement that may contain a lease under the updated lease definition, including embedded leases within IT and service contracts.
- Assess Exemption Eligibility: Document which leases qualify for short-term or low-value exemptions, and retain that documentation as part of the audit file.
- Determine Discount Rates: For each lease being brought on the balance sheet, determine the rate implicit in the lease if it is readily determinable. If it is not, use either the incremental borrowing rate or the obtainable borrowing rate on a lease-by-lease basis.
- Review Revenue Contracts: For entities with complex contracts, map each arrangement against the five-step model and document the judgments applied.
- Stress-Test Existing Models: If spreadsheets are currently in use, identify where they will fail under the expanded disclosure requirements, particularly for lease modifications and portfolio-level reporting.
- Reduce Manual Extraction: Establish a repeatable, structured process for extracting lease and contract data that does not rely on manual re-entry each period.
- Plan for the Disclosure Requirement: Lease disclosures are more extensive than most entities have produced before. Build and review disclosure templates before year-end, not after.
For chartered accounting firms, the additional step is standardisation: a consistent process and consistent outputs across clients, so that busy season volume does not translate directly into busy season error.
Crunchafi's lease accounting software is purpose-built to automate the calculations, journal entries, and disclosures required under FRS 102 Section 20, so your team spends less time on calculations across every client engagement. Request a demo to see how Crunchafi supports FRS 102 lease compliance.
Frequently Asked Questions
What is FRS 102?
FRS 102 is the Financial Reporting Standard applicable in the UK and Ireland, covering most entities that do not apply IFRS. It governs how statutory accounts are prepared and filed with Companies House.
Is FRS 102 the same as IFRS?
No. FRS 102 is a simplified framework designed for non-publicly accountable entities. The March 2024 amendments align certain areas, particularly lease accounting and revenue recognition, more closely with IFRS 16 and IFRS 15, but FRS 102 remains a distinct standard with its own requirements and thresholds.
Who must comply with the 2026 changes?
Any entity preparing statutory accounts under FRS 102 for periods beginning on or after 1 January 2026. This includes large and small entities across the UK and Ireland. Micro entities filing under FRS 105 are largely unaffected, though some elect to file under FRS 102 Section 1A regardless.
How does the 2026 update affect lease accounting?
Under the updated Section 20, the lessee distinction between operating and finance leases is removed. As a result, more leases must now be recognised as right-of-use assets and corresponding lease liabilities, subject to the short-term and low-value recognition exemptions.
Entities must calculate the present value of future lease payments using a discount rate, and produce expanded disclosures, all with an audit-ready record of the judgments made.
Related resources
Accounting for GASB 87 and GASB 96\ \ Lease Accounting
What are Right of Use Assets?\ \ Lease Accounting
Why CPA Firms Must Embrace Automation & Client-Centric Audits\ \ Lease Accounting
Get the good sheet in your inbox
First Name*
Last Name*
Email*